
You found a flight that fits your dates, your route, and the trip you want to take. Then you saw the total. Paying the full fare today would squeeze money you need for rent, bills, or the rest of the trip, but waiting could mean losing the seat or watching the price move. That tension is why book now pay later flights appeal to so many people. They let you secure a ticket now and spread the cost over short installments. They also add a lender, a repayment schedule, and extra refund steps between you and the airline. Used carefully, that trade-off can work. Used casually, it can leave you paying for a trip you are no longer taking.
Table of Contents
- Why Travelers Are Choosing Book Now Pay Later Flights
- How BNPL Flight Payments Actually Work
- Comparing Major BNPL Providers for Flights
- How to Use BNPL at Flight Checkout
- The Hidden Risks of Interest-Free Flight Financing
- How to Choose the Right BNPL Plan for Your Trip
- Safe BNPL Flight Booking Checklist
- Frequently Asked Questions About BNPL Flights
Why Travelers Are Choosing Book Now Pay Later Flights
A traveler booking an overseas trip for a family wedding often faces the clearest version of this problem. The flights are not optional in the way a new gadget is optional, and the best itinerary may not stay available while you save month by month. Book now pay later flights offer a way to lock in the booking, pay a portion at checkout, and clear the rest over a defined period. You're not reducing the fare. You're changing when the money leaves your account, which can matter when hotels, transfers, and travel insurance also need attention.
That demand is real, and it comes with understandable caution. In an Amadeus traveler study conducted in 2021, 40% of respondents said BNPL would encourage them to book travel during the summer and 62% said they would be prepared to book summer travel if airlines offered a pay when you fly option, while 54% identified the refund process as their greatest concern, 44% cited interest rates, and 31% worried about getting into too much debt. Read together, those figures are more useful than any promise about effortless travel. Travelers want flexibility on payment, but they worry most about what happens when plans change.
Why the Appeal Makes Sense
Splitting a large fare can help you book earlier, choose better flight times, and avoid putting the full amount on a card in one transaction. It can also protect short-term cash flow if payday falls after a limited fare expires. That logic is similar to checking flight deals for this weekend before committing, because timing and price should be considered together. A lower fare paid badly can cost more than a slightly higher fare paid on terms you fully understand.
Paying in installments solves a timing problem. It does not make an unaffordable flight affordable.
That distinction is where patient decision-making starts. Before you choose BNPL, you need to know whether interest applies, what late fees can be charged, how eligibility is checked, and how a refund reaches the lender. The airline still controls the ticket rules, while the payment provider controls the loan. If those two systems do not move together after a cancellation, you may need to manage both. That is not a reason to reject BNPL automatically. It is a reason to treat it as a financing decision, not as a harmless checkout button.
How BNPL Flight Payments Actually Work
Most book now pay later flights use a structure called pay in four. You select the BNPL option at checkout, complete an eligibility check, and make the first payment before the booking is financed. The provider pays the airline or booking platform, the ticket is issued under the airline's normal terms, and you repay the provider on a fixed schedule. You're buying the same ticket you would buy with a card, but your payment obligation sits with the lender instead of ending at purchase.
The flow below shows the basic sequence from checkout to confirmation.
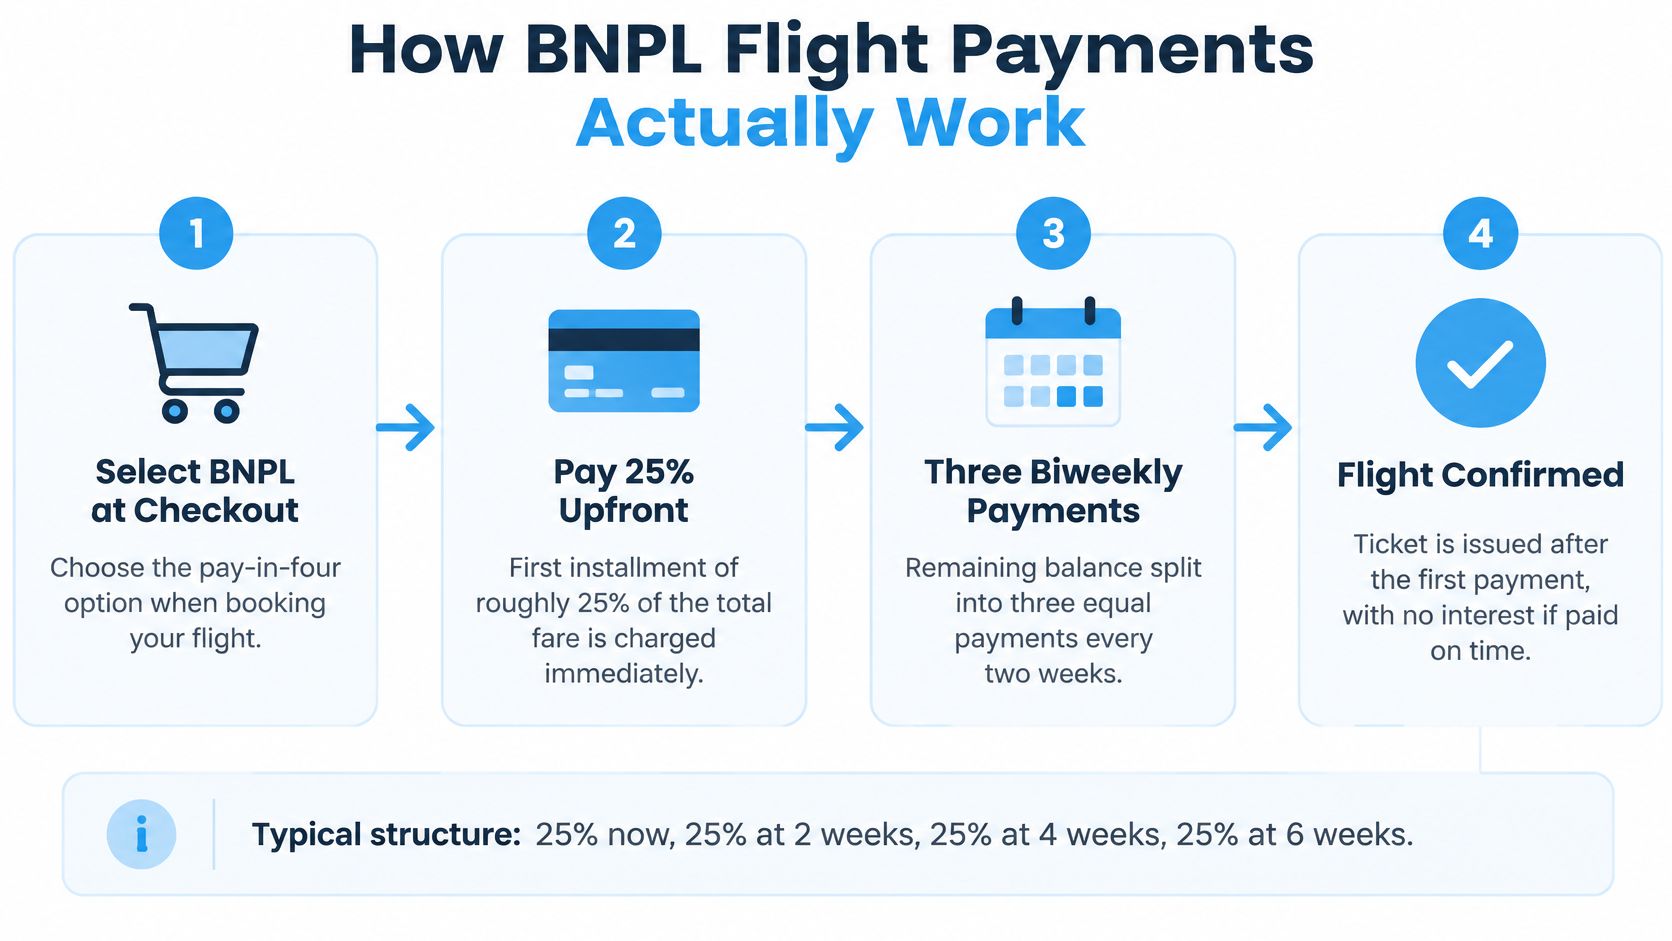
The most common technical structure is a pay-in-four loan where you pay approximately 25% at purchase followed by three equal installments generally scheduled at two-week intervals, and in the CFPB dataset covering six major BNPL providers in 2023, 4.1% of pay-in-four loans incurred a late fee, down from 5.2% in 2022, while late-fee revenue represented 0.18% of gross merchandise volume. That single picture captures both the attraction and the risk. The schedule is short and predictable, but missed payments are not rare enough to ignore.
What Interest-Free Really Means
An interest-free plan can still charge fees. A late fee may apply if a payment fails, your bank rejects the debit, or you forget that the due date arrives before payday. Some longer installment products work differently from pay in four and may charge interest, so you shouldn't assume every plan shown at checkout has identical terms. Read the total payable amount, not just the amount due today.
It also helps to separate payment flexibility from booking flexibility. BNPL does not turn a basic, nonrefundable ticket into a flexible ticket. It doesn't remove baggage charges, guarantee a free date change, or override the airline's schedule-change policy. Travelers who also want to understand paying without a conventional card can read guidance on how to book a hotel without a credit card, but flights have a sharper complication. Airlines issue, change, and refund tickets under fare rules, while the BNPL provider collects what you owe under a separate agreement.
Two Contracts in One Purchase
Think of the transaction as two linked contracts. The first is your ticket contract with the airline or agency. The second is your financing contract with providers such as Klarna or Affirm, depending on the checkout. If everything goes to plan, you barely notice the separation. If the flight is canceled or you request a refund, that separation becomes the whole problem, because the airline must process its side before the lender can reconcile yours.
Comparing Major BNPL Providers for Flights
Providers differ less in their marketing than in their fine print. At flight checkout you may see names such as Klarna, Affirm, Afterpay, or a regional option such as SeQura, depending on the airline, agency, and country. You cannot safely compare them by the first installment alone. The questions that matter are whether interest can apply, what kind of credit check is used, what happens after a missed payment, and how refunds are treated when an airline returns money.
Travel has become a visible market for these companies. CNBC reported that Klarna's travel-booking value increased 50% year over year and Affirm's travel and ticketing volume rose 38% year over year in the fourth quarter of 2024 and exceeded $1 billion, while a March 2025 NerdWallet report cited by CNBC found nearly one in five American travelers planned to use BNPL for summer vacations. Growth tells you the option is established. It does not tell you a particular plan is suitable for your fare, your bank balance, or your tolerance for refund delays.
BNPL Provider Comparison for Flight Bookings
| Provider | Interest | Credit Check | Late Fee | Refund Handling |
|---|---|---|---|---|
| Klarna | Check the specific product at checkout, because terms vary by plan and market | Confirm whether the check is soft or hard before applying | Check the amount and grace period in the agreement | Ask how airline refunds reduce the balance and when installments pause |
| Affirm | Confirm whether the offer is interest-free or interest-bearing before accepting | Confirm inquiry type and reporting practice for the product offered | Review the missed-payment terms shown for your plan | Verify whether refunds go to the loan first and how overpayments are returned |
| Afterpay | Review the product disclosure rather than relying on checkout headlines | Ask what eligibility check applies to flight purchases | Check late-fee caps and failed-payment treatment | Confirm the evidence needed when a merchant refund is delayed |
| SeQura | Review whether the selected installment term carries interest | Confirm eligibility requirements in your country of residence | Read the schedule of charges before confirming | Ask who contacts the booking platform if a refund has not arrived |
This table is deliberately cautious. Provider terms can vary by product, merchant, country, purchase amount, and your eligibility, so a generic promise from a comparison page is not enough. The legally meaningful terms are the ones presented for your plan at checkout. Save them before you pay.
How to Read the Differences
Interest and fees determine the true cost if anything goes off schedule. A plan that costs nothing when paid perfectly may become expensive after a failed debit. Credit checks and reporting determine whether applying or repaying can appear in your credit file. Refund handling is the category travelers most often skip and later regret.
Checkout rule: If you cannot find the refund process in plain language before paying, treat that as missing information, not as a small detail.
Availability can also be a trap. The first provider shown may be the booking platform's commercial partner, not the best fit for you. Compare the full agreement, the due dates against your income, and the airline's fare rules. A provider with clear refund communication and payment dates you can meet is usually a safer choice than one chosen only because it approved you fastest.
How to Use BNPL at Flight Checkout
Start by choosing the flight as if you were paying in full. Check the airline, baggage rules, change conditions, and whether the fare is refundable in cash, refundable as credit, or not refundable at all. Only then look at payment. If you reverse that order, the installment amount can make a restrictive ticket look safer than it is.
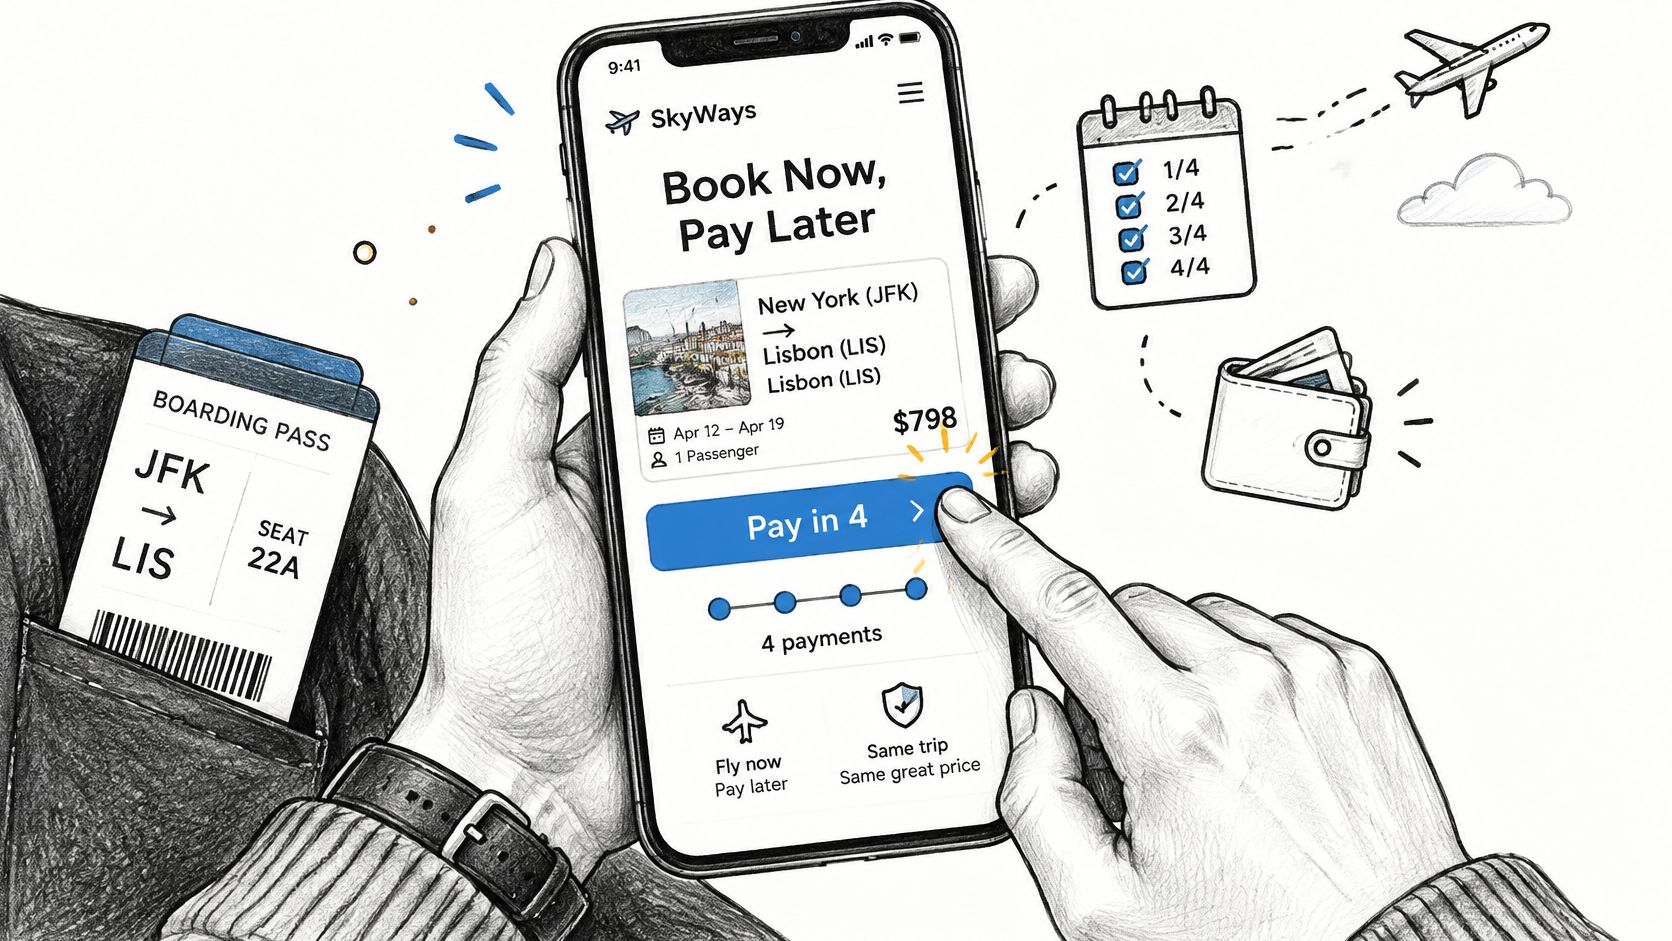
The booking usually happens on a phone or laptop, with the payment choice appearing near the final step.
A Careful Checkout Sequence
- Confirm the ticket terms first. Note whether cancellation produces a cash refund, a travel credit, or no refund. BNPL does not improve those outcomes.
- Select BNPL and complete eligibility. The provider may ask for identity, contact, and payment details, then explain whether the check is a soft or hard inquiry.
- Read the repayment schedule. Check the amount due today, every later due date, the payment method that will be charged, and the maximum late fee.
- Find the refund wording. Look for what happens if the airline cancels, the agency issues credit, or only part of the fare is returned.
- Save the agreement and confirmation. Keep screenshots or downloads showing the plan, ticket number, fare rules, and merchant name exactly as presented.
Approval is the point where many people stop reading. Resist that. You're not done when the provider says yes. You're entering a schedule that will continue even if your travel plans become complicated, so confirm that reminders are enabled and the charged account will have enough money on every due date. If the installments fall just before payday, consider paying in full, choosing a different date, or waiting. Convenience disappears quickly when a small timing mismatch creates fees.
The short video below gives another view of how the checkout choice appears in practice.
After booking, verify two separate confirmations. The airline or agency should confirm the ticket, and the lender should confirm the loan schedule. If either arrives without the other, contact the relevant company promptly and keep a record. Do not assume an itinerary email proves the financing terms, or a loan email proves the ticket was issued.
The Hidden Risks of Interest-Free Flight Financing
The phrase interest-free invites a dangerous shortcut. It sounds like the cost of borrowing is zero, so the decision feels low-risk. For flights, the bigger exposure often comes from timing. Your installments follow the lender's calendar, while airline refunds follow airline operations, agency processing, and fare rules. When those calendars disagree, you can be out of pocket for a flight you cannot take.
The comparison below separates what looks safe from what can still go wrong.
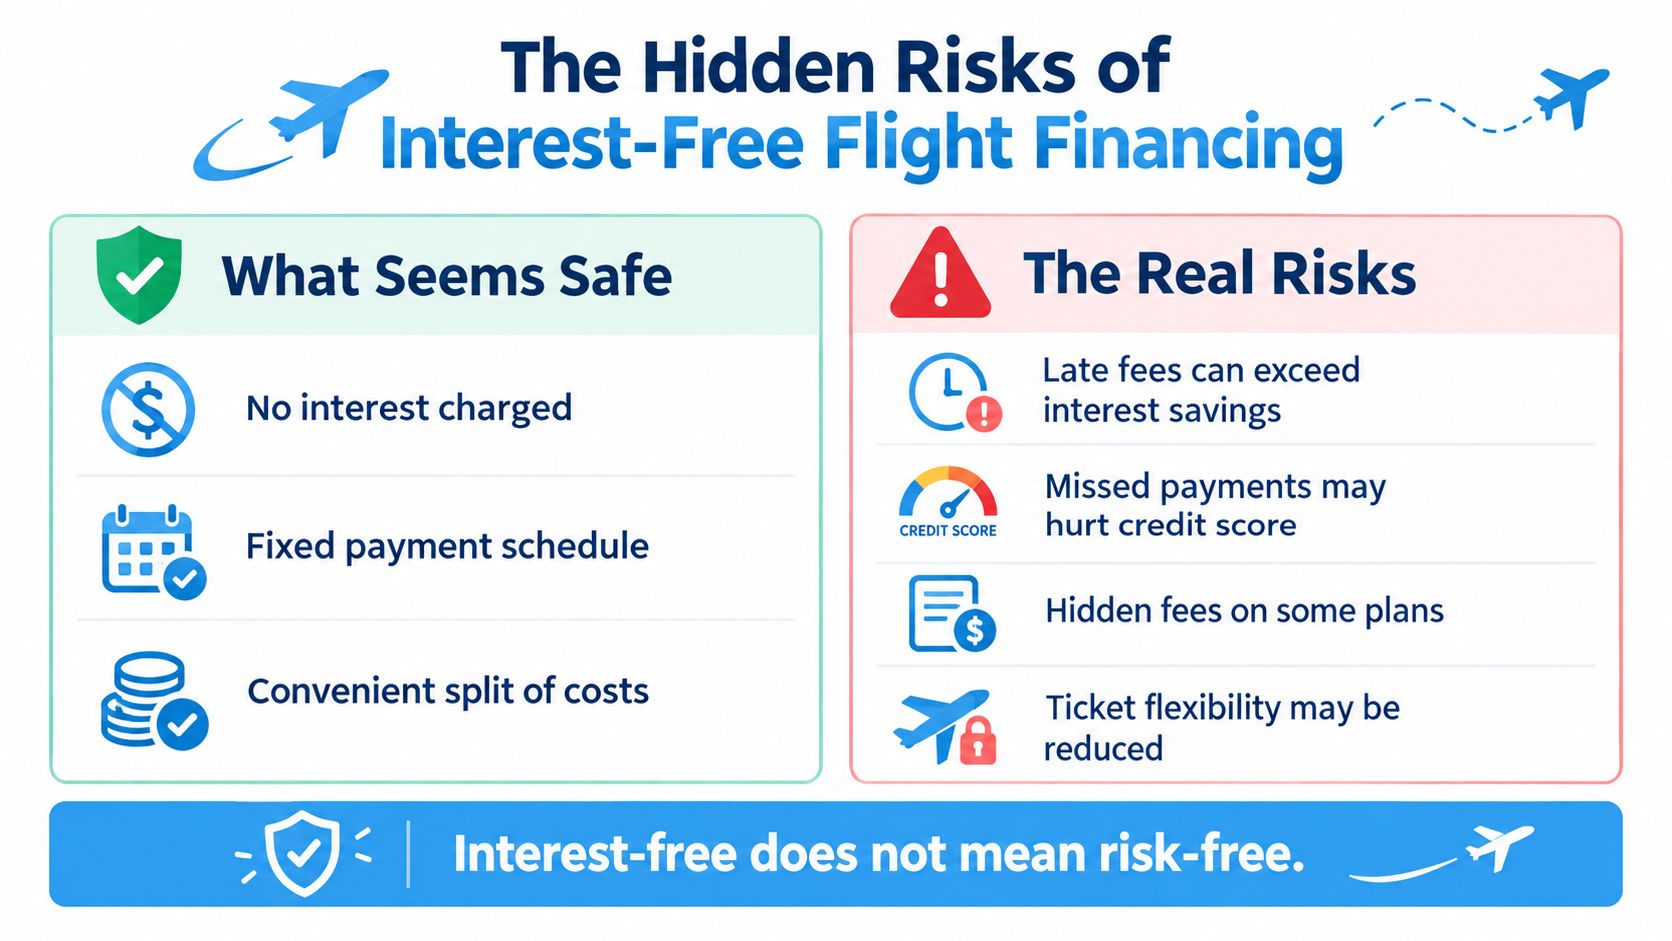
This is not a theoretical concern. Consumer Reports documented cases in which travelers continued owing installments after a trip was canceled because the lender had not yet received or processed the refund, and consumer advocates warn that BNPL transactions may be harder to reverse than card purchases, potentially creating late fees, repeated customer-service contacts, and credit damage while a refund is pending. You may know the airline owes you money. The lender may still expect the next installment until its own records show the refund.
Four Refund Situations That Behave Differently
- The airline cancels and offers a cash refund: Ask the airline or agency where the money will go, then tell the lender immediately and request that payments be paused or adjusted.
- The airline offers travel credit: Credit may satisfy the airline's ticket obligation while giving the lender no cash to apply to your loan. Your installments can continue.
- You cancel voluntarily: The fare rules control how much, if anything, comes back. A partial refund may reduce the loan without eliminating it.
- The booking platform processes the refund: The money may need to move from airline to platform to lender. Each handoff adds a possible delay and another support team.
Do not stop paying because a refund was promised. Ask the lender for written confirmation that the balance is paused, reduced, or closed, and keep the airline's cancellation notice, refund reference, chat transcripts, and emails. If a due date is approaching and no written pause exists, contact the lender before the payment fails. A short explanation after a missed payment is weaker than evidence you raised the issue in advance.
An airline refund and a closed BNPL loan are related events. They are not the same event.
There's also a behavioral risk. Small installments can make several purchases feel manageable until their due dates cluster together. Flights are especially easy to justify because the trip feels distant and worthwhile. Set a rule before checkout that the fare must fit your normal budget without relying on overtime, a future refund, or another form of credit. If repayment depends on everything going right, the plan is fragile.
How to Choose the Right BNPL Plan for Your Trip
Choose by total payable amount and refund clarity, not by the smallest amount due today. Two plans can finance the same ticket and behave very differently if you miss a payment or the airline changes the schedule. The right plan is the one whose dates fit your income, whose fees you can state plainly, and whose refund process you understand before the ticket is issued.
The checklist below turns that principle into a quick comparison you can use at checkout.
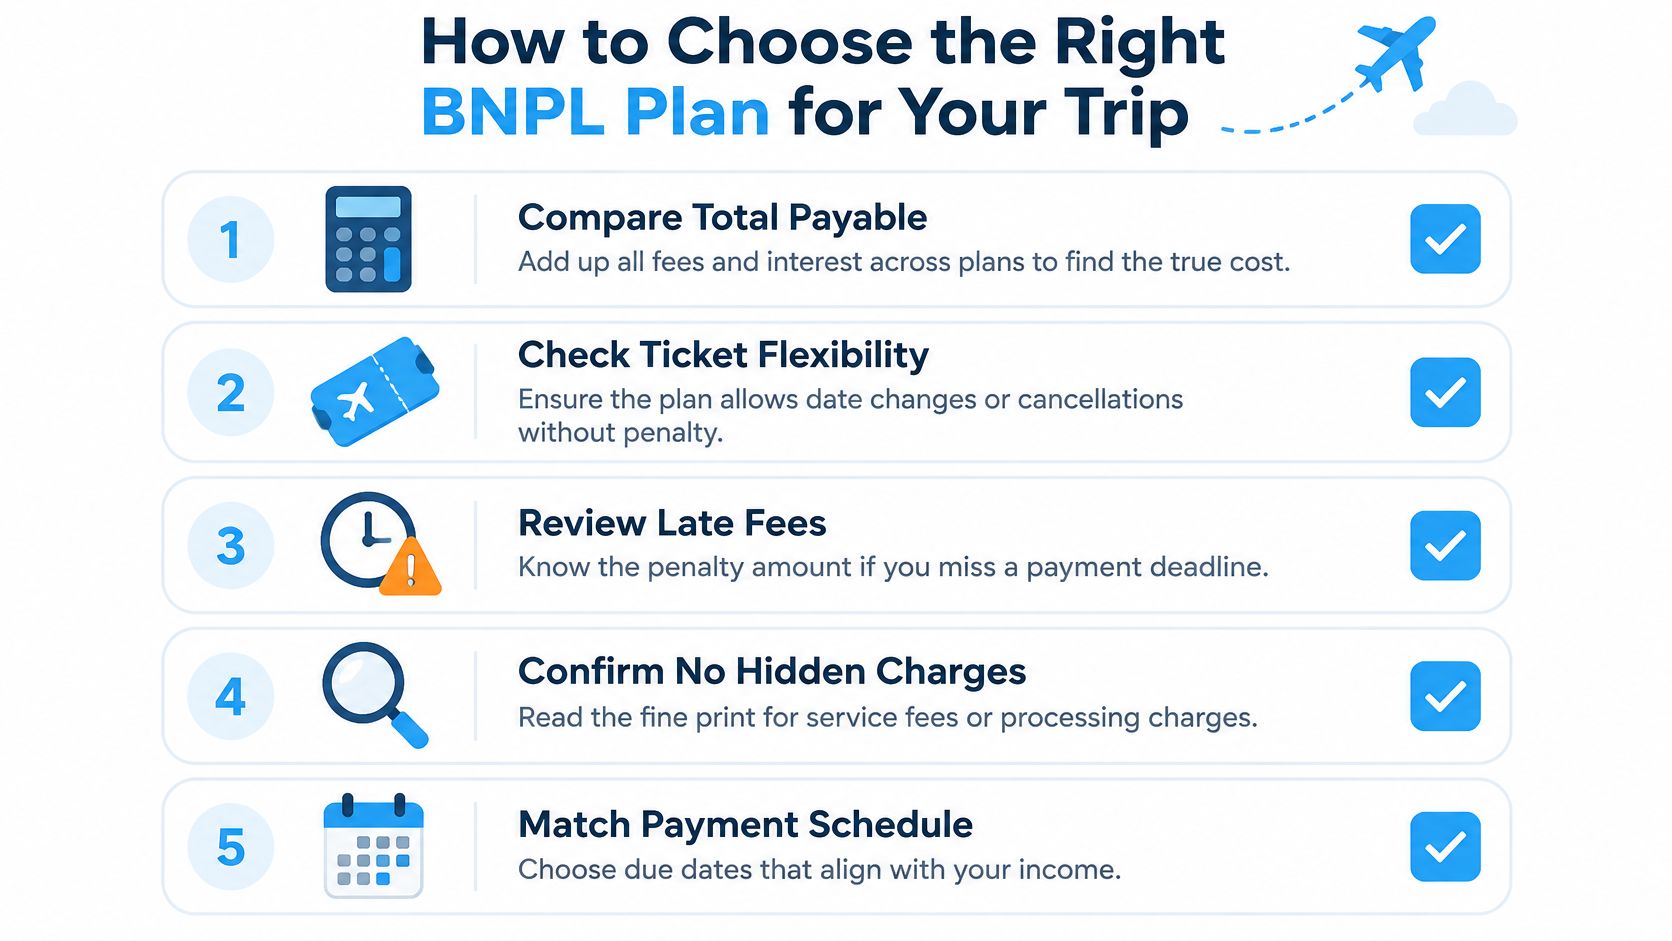
Credit reporting deserves a direct question, not an assumption. Federal Reserve Bank of Philadelphia research found that, among consumers with established credit profiles, BNPL use did not appear to significantly change credit profiles in the short term, however BNPL users showed higher bankcard utilization, more accounts with past-due balances, and larger past-due balances, while credit-bureau reporting varies by provider and product. In practical terms, ask whether the eligibility check is soft or hard, whether on-time payments are reported, when delinquency is reported, and whether unpaid balances can be sent to collections.
Questions That Reveal the Better Offer
Start with the ticket. A flexible fare may be worth more than a restrictive fare with attractive installments, especially for family events, work travel, or itineraries vulnerable to disruption. Then examine the plan. Can you pay early without penalty? What happens after a partial refund? Which company do you contact first if the airline cancels? If the answers are buried or inconsistent, another payment method may be safer.
Timing your purchase can also reduce the amount you need to finance, so it helps to consider the best day of week to book flights alongside the payment terms. Don't let a financing approval rush you into a fare you haven't compared. BNPL works best when the underlying flight is already a sound purchase and the installments merely spread a cost you could responsibly cover over the short repayment window.
Safe BNPL Flight Booking Checklist
Use this checklist at the point where the checkout asks you to confirm. It brings the fare, the loan, and the refund path into one view, which is exactly what the separate airline and lender screens often fail to do. If you cannot answer an item, pause before paying.
Before You Confirm
- Verify the fare rules: Know whether cancellation returns cash, issues credit, allows date changes, or forfeits the ticket value.
- Confirm the total payable: Add every installment and any interest or account fees shown in the agreement. Don't compare only the first payment.
- Check every due date: Match the schedule against payday and existing bills. Enable reminders and use an account that will reliably have funds.
- Identify the credit treatment: Confirm whether the check is soft or hard, whether payments are reported, and when missed payments may be reported.
- Read the missed-payment terms: Know the late fee, any grace period, and whether the provider can restrict future use or send a balance to collections.
If Plans Change
- Notify both sides: Contact the airline or booking platform about the ticket and the lender about the loan. One conversation does not update both systems.
- Get the refund destination in writing: Ask whether money goes to the lender, the original payment method, or an agency account first.
- Request a loan pause in writing: Ask the lender to confirm whether upcoming installments are paused, reduced, or still due while the refund is processed.
- Keep the evidence together: Save the itinerary, fare rules, cancellation notice, refund reference, loan agreement, and support messages in one folder.
- Watch for the closing confirmation: Do not consider the matter finished until the lender shows the correct balance, including zero if the full amount was refunded.
That final point is the habit that prevents most avoidable trouble. Travelers often follow the flight status closely and the loan status loosely. For book now pay later flights, both deserve the same attention until the money and the ticket records agree.
Frequently Asked Questions About BNPL Flights
Can I use BNPL for international flights?
Often yes, if the airline or booking platform offers it for your route, country, and purchase. Eligibility and provider availability vary, and the ticket still follows the airline's international fare rules.
What happens if my flight is canceled?
Contact the airline or agency for the ticket decision and the lender for the loan. Ask for written confirmation that installments are paused or adjusted. Do not assume a refund automatically closes the balance.
Is BNPL better than a credit card?
Neither is automatically better. BNPL can provide a fixed short schedule, while a card may offer different dispute and refund processes. Compare total cost, reporting, fees, and how each option handles cancellation.
Does paying early help?
It can reduce the chance of a missed due date, but check the agreement for how early payments are applied. Keep confirmation that the balance has closed.
Compare the fare first and the installment plan second, then book only when the refund path is clear on both sides. At Easy Travel Bookings, you can compare flights from trusted airlines and booking providers in one search before proceeding to the seller's checkout to review its payment options. Start your search there, choose a ticket that fits your plans, and use the checklist above before selecting any pay-later offer.